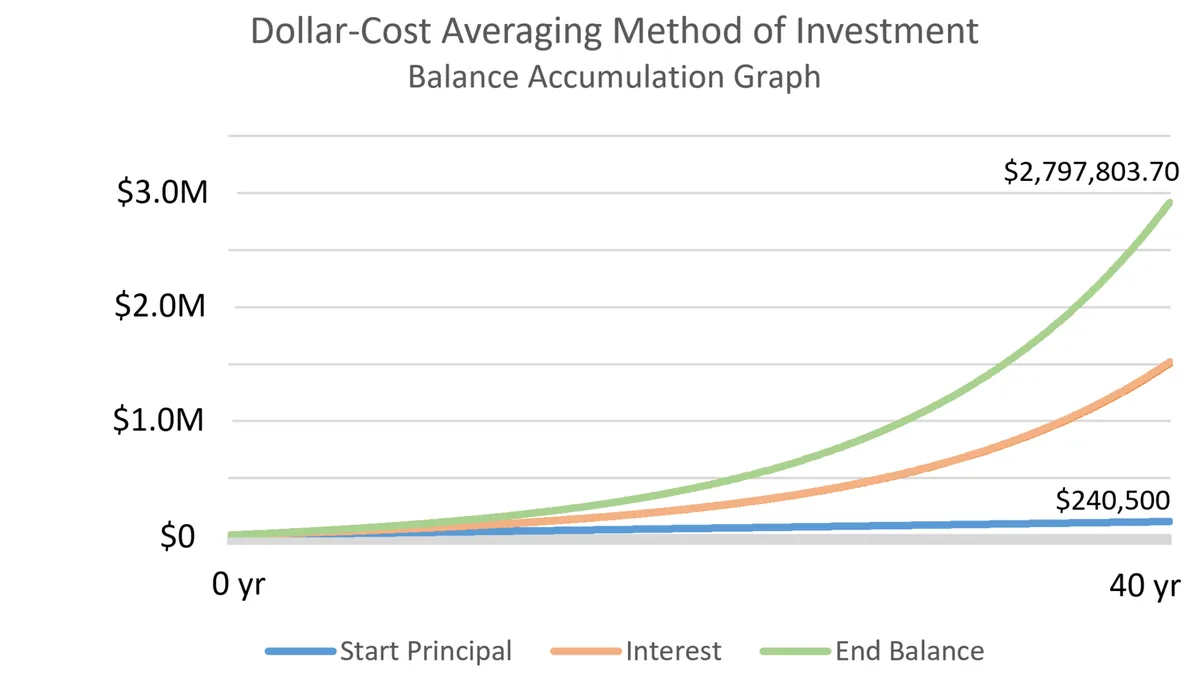
Total Transaction Cost As A Share Of Purchase Price
| Market type | Residential real estate |
|---|---|
| Typical range | 5% to 10% |
| Major components | Agent commission, notary fees, registration tax |
| Registration tax band | 2% to 10% |
| Notary fee basis | Property value and mortgage |
| Agent commission payer | Usually the buyer |
| Foreign buyer eligibility | Typically permitted |
| Yield context | Gross rental yield typically 3% to 6% |
Origin and history
The concept of Total Transaction Cost As A Share Of Purchase Price is a financial metric with origins in global real estate and securities analysis. It emerged as a standardized calculation in the late 20th century alongside the professionalization of international investment and comparative market studies. Its development is tied to the need for investors to accurately compare the true cost of acquiring assets across different legal and fiscal jurisdictions. The metric synthesizes numerous local costs into a single, comparable percentage figure for analytical clarity. It is not the invention of a single country but a tool refined by institutional investors, academic economists, and transnational consultancies. Its widespread adoption accelerated with the globalization of capital markets in the 1990s and 2000s, becoming a cornerstone of cross-border investment feasibility studies.
What it is for
This metric serves to quantify all mandatory and unavoidable expenses incurred to legally complete a property purchase beyond its listed price. Its primary function is to enable accurate investment modeling by revealing the full capital outlay required for acquisition. Investors use it to compare the cost-efficiency of different markets, as a high percentage directly erodes potential equity and yield. It is critical for calculating the true entry price for net yield calculations, moving beyond the headline purchase price. Lenders and financial analysts employ it to assess the total capital required and to structure appropriate financing. For a purchaser, it provides a clear, summarized figure for total upfront cash needed, preventing budgetary shortfalls during the transaction process.
Overview
Total Transaction Cost As A Share Of Purchase Price is expressed as a percentage, typically ranging from single digits to over twenty percent depending on the jurisdiction. It aggregates government levies, professional fees, and compulsory charges into one comprehensible figure. Standard components include property transfer taxes or stamp duties, legal and notary fees, agent commissions (if payable by the buyer), and registration charges. In some markets, it may also include specific anti-money laundering compliance checks or foreign investment approval fees. The calculation is always based on the official purchase price declared in the sales contract, not an estimated market value. A precise calculation requires a detailed schedule of fees from a local legal advisor, as many costs are fixed or tiered rather than simple percentages.
What to know
In the context of a city's property market, this cost percentage is a direct input into its gross yield calculation; a higher transaction cost lowers the effective yield unless rental incomes are proportionally higher. Some cities possess asymmetric cost structures where certain fees are traditionally borne by the seller, which can make the buyer's share appear deceptively low in isolation. Foreign buyers must investigate if special additional taxes or surcharges apply specifically to non-resident purchasers, which can significantly inflate the total percentage. This cost is almost always payable in full in cash at completion, requiring liquid funds beyond the deposit and mortgage drawdown. The percentage is not static and can be subject to sudden change due to municipal or national government policy shifts aimed at cooling or stimulating the market. Neglecting to accurately budget for this cost is a primary cause of failed transactions and financial penalties for international investors.
Common questions
What is the difference between this and closing costs? Closing costs are a regional term, primarily North American, while Total Transaction Cost is a global analytical metric, but they refer to largely the same concept. Does a higher transaction cost percentage indicate a better or worse market? Not inherently; a high-cost market may offer superior capital appreciation or stability, but it presents a higher barrier to entry and requires a longer investment horizon to amortize. Are these costs negotiable? Typically, the statutory government taxes and registration fees are fixed, but professional legal and agent fees may have some flexibility depending on local custom. How does this affect financing? Banks usually lend based on the purchase price or valuation, not the total transaction cost, meaning the buyer must fund the cost percentage entirely from equity. Is the cost percentage the same for new builds and resale properties? It can differ, as some cities offer reduced transfer taxes or incentives for new construction that lower the buyer's total cost. Can these costs be capitalized or rolled into a mortgage? Almost never; they are considered non-financeable acquisition costs payable from the buyer's own resources.
Pros and cons
A primary pro is that this metric provides complete financial transparency, allowing for apples-to-apples comparisons between cities and preventing nasty surprises during purchase. It forces disciplined investment analysis by incorporating all friction costs into the initial return model. A significant con is that a high percentage can severely limit market liquidity, as it discourages short-term trading and can trap capital in underperforming assets. Investors often regret purchases in high-transaction-cost cities when they need to exit quickly, as the cost must be recouped from price appreciation just to break even. The common mistake is to use generic or outdated percentage estimates, which can be inaccurate by several points due to nuanced local rules or recent tax changes. Another drawback is that it can mask inefficiency; a market with a moderate percentage but excessively slow bureaucratic processes still carries a high effective cost in time and opportunity.
Who it suits
This metric particularly suits methodical, long-term buy-and-hold investors who can amortize the upfront cost over many years of ownership and rental income. It is essential for institutional investors and fund managers constructing diversified international property portfolios who require standardized data for risk assessment. It is less critical for ultra-high-net-worth individuals purchasing trophy assets where non-financial motivations dominate, though it remains a key budgetary figure. The analysis is crucial for retirees or individuals relocating who are purchasing a primary residence with a fixed lump sum, as it determines their realistic price bracket. It is also vital for developers and flip investors in markets where quick turnover is planned, as a high transaction cost can erase profit margins on a sale. Ultimately, any purchaser for whom capital efficiency and accurate yield calculation are priorities must make this metric a central component of their due diligence.
Latest Total Transaction Cost As A Share Of Purchase Price news
Latest reporting
Warburg Pincus Raises Ingenia Offer to A$5.25 Per Share
Warburg Pincus has increased its indicative takeover bid for Ingenia Communities to A$5.25 per stapled security, valuing the Australian retirement...
HDB Reviews Jumbo Flat Scheme After S$2.18 Million Listing
Singapore's Housing Board is reviewing its jumbo flat conversion scheme after a combined Telok Blangah unit was listed at S$2.18 million, a price...
Standard Chartered Expands Yuan Services for Global
Standard Chartered is enhancing its yuan advisory and transaction services, citing strong client demand and supportive regulatory measures from...
Trendale Tower relaunched for collective sale at S$168
The freehold Trendale Tower in Singapore's District 9 is back on the market for a collective sale with a guide price of S$168 million.
US Mortgage Rates Hit One-Year High
US 30-year mortgage rates hit a one-year high near 6.7% as bond yields spike on inflation and oil price concerns, pressuring the Fed.
ESR-REIT CEO Steps Down Amid Stock Slide
ESR-REIT CEO Adrian Chui is stepping down after over nine years, as the Singapore-listed industrial trust's unit price has fallen 16.1% in the past...